Table of contents
The 2025/26 married person's allowance is HK$264,000, rising to HK$290,000 from 2026/27, and cannot be combined with the basic allowance. Joint assessment suits cases where one spouse's income is clearly lower; when both spouses have high incomes, separate assessment usually saves more tax. Joint assessment must be applied for again every year.
Key takeaways
- The 2025/26 married person's allowance is HK$264,000; from 2026/27 it rises to HK$290,000.
- The married person's allowance cannot be combined with the basic allowance; you must choose one.
- Joint assessment does not always save tax: it is more favourable when one spouse has a low income; when both have high incomes, separate assessment is usually better value.
- The IRD will automatically work out the more favourable method, but we still suggest running the numbers yourself before choosing.
How much is the married person's allowance?
According to information from the IRD, the married person's allowance is an allowance for married taxpayers under Hong Kong's salaries tax system. The amount is HK$264,000 for 2025/26 and rises to HK$290,000 from 2026/27.
| Type of allowance | 2025/26 | 2026/27 |
|---|---|---|
| Married person’s allowance | HK$264,000 | HK$290,000 |
| Basic allowance (for reference) | HK$132,000 | HK$145,000 |
Important: The married person's allowance and the basic allowance cannot be claimed together; you can only choose one. The married person's allowance is usually chosen as the amount is higher.
The married person's allowance for 2025/26 is HK$264,000, rising to HK$290,000 from 2026/27. This allowance cannot be combined with the basic allowance: a married taxpayer who claims the married person's allowance can no longer claim the basic allowance.
For an overview of how salaries tax is calculated overall and the other allowances, see Salaries tax calculation and personal allowances: a complete guide.
Conditions for claiming the married person's allowance
To claim the married person's allowance you must meet one of the marital status conditions (living together or supporting the spouse) and one of the assessment conditions (the spouse has no salaries tax income, or you have elected joint assessment or Personal Assessment). Both categories of condition must be met.
Under section 29 of the Inland Revenue Ordinance, the taxpayer must, during that year of assessment, meet one of the following marital status conditions:
- Married and living with the spouse; or
- Married but living apart from the spouse, while supporting or financially supporting the other.
In addition, you must meet one of the following assessment conditions:
- The spouse has no chargeable salaries tax income in that year;
- The taxpayer and spouse have elected joint assessment; or
- The taxpayer and spouse have jointly elected to be assessed under Personal Assessment.
Separate vs joint assessment: what is the difference?
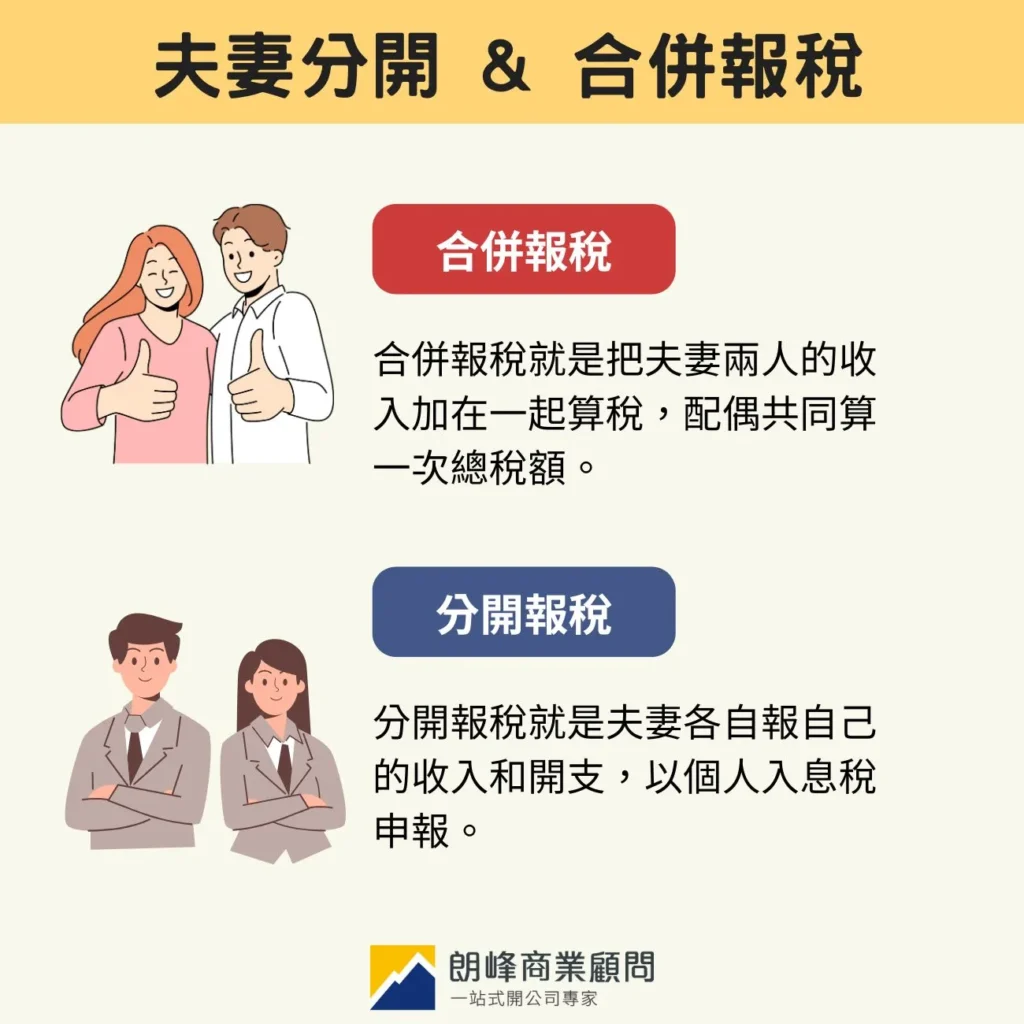
Married people in Hong Kong can choose their filing method each year. Each method suits different situations, so understand the differences before choosing.
| Method of assessment | Calculation method | Allowance amount | Suitable situations |
|---|---|---|---|
| Separate assessment | Each spouse reports income and deductions separately | Each uses the personal basic allowance of HK$132,000 | Both spouses have similar or high incomes |
| Joint assessment | Both spouses' incomes are added together | Share the married person's allowance of HK$264,000 | One spouse has a clearly lower income or close to zero |
Points to note for joint assessment:
- You must elect it in the tax return every year; it does not carry over automatically
- Tick the box to apply for joint assessment in Part 4.4 of the Tax Return - Individuals (BIR60)
- If both spouses happen to tick it, the IRD will automatically allocate it to the more favourable spouse and notify them to amend
Which filing method saves more tax?
The two scenarios below are calculated at 2025/26 tax rates (basic allowance HK$132,000, married person's allowance HK$264,000, excluding other deductions).
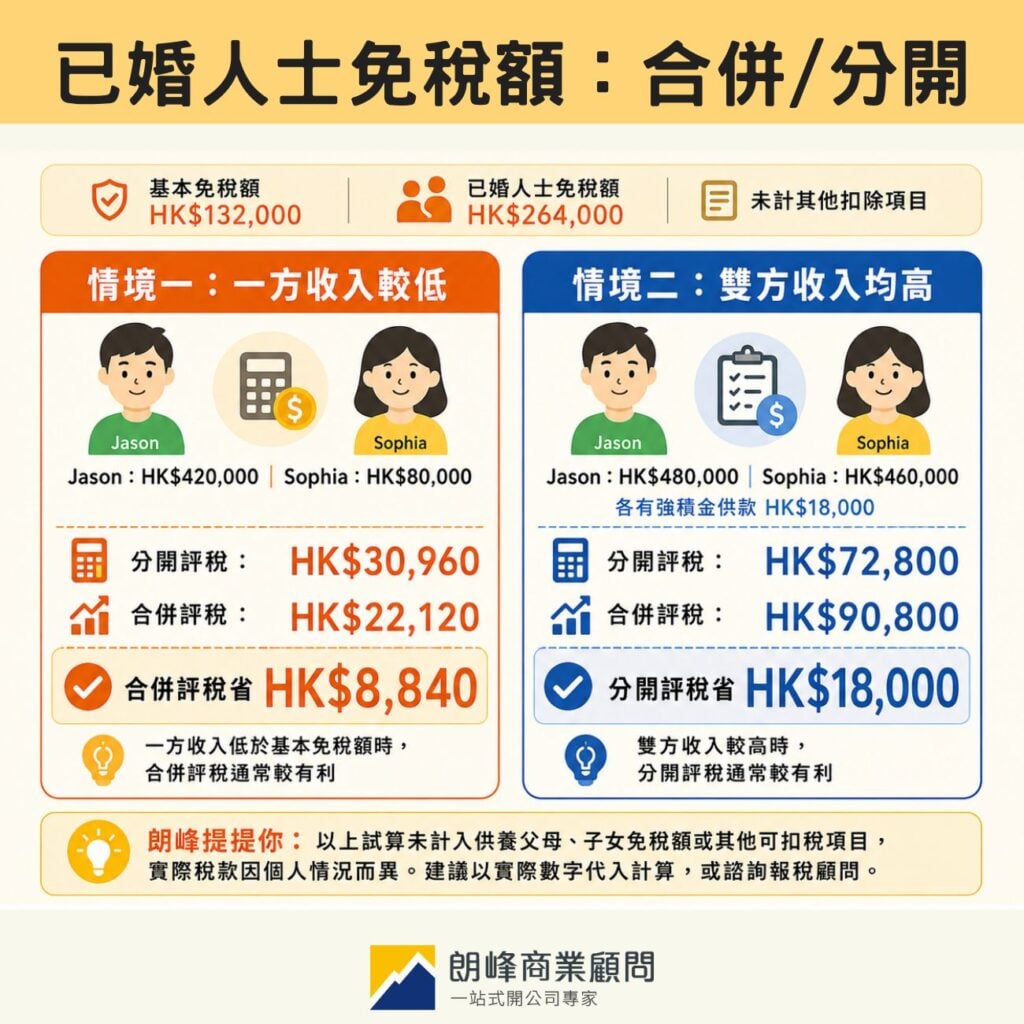
Scenario 1: one spouse has a lower income - joint assessment is more favourable
Jason's annual income is HK$420,000 and Sophia's is HK$80,000.
Separate assessment:
- Jason: net chargeable income HK$288,000 (420,000 − 132,000), progressive tax HK$30,960
- Sophia: income of HK$80,000 is below the basic allowance, tax HK$0
- Total: HK$30,960
Joint assessment:
- Combined income HK$500,000, less married person's allowance HK$264,000
- Net chargeable income HK$236,000, progressive tax HK$22,120
✅ Joint assessment saves HK$8,840
When one spouse's income is below the basic allowance, joint assessment can make use of the higher married person's allowance (HK$264,000) and the tax is usually lower than under separate assessment. For example, with annual incomes of HK$420,000 and HK$80,000, joint assessment saves about HK$8,840 (2025/26 calculation).
Scenario 2: both spouses have high incomes - separate assessment is more favourable
Jason's annual income is HK$480,000 and Sophia's is HK$460,000, each with mandatory MPF contributions of HK$18,000.
Separate assessment:
- Jason: net chargeable income HK$330,000 (480,000 − 18,000 − 132,000), tax HK$38,100
- Sophia: net chargeable income HK$310,000 (460,000 − 18,000 − 132,000), tax HK$34,700
- Total: HK$72,800
Joint assessment:
- Combined income HK$940,000, less HK$36,000 and married person's allowance HK$264,000
- Net chargeable income HK$640,000, progressive tax HK$90,800
✅ Separate assessment saves HK$18,000
When both spouses have high incomes, combining their incomes pushes them into higher progressive rate bands and the overall tax actually increases. For example, with annual incomes of HK$480,000 and HK$460,000, separate assessment saves about HK$18,000 compared with joint assessment (2025/26 calculation, each including the mandatory MPF contribution deduction).
💡 SetupHK tip: The above calculations do not take into account the dependent parent or child allowances or other deductible items; actual tax varies with individual circumstances. We suggest substituting your actual figures, or consulting a tax adviser.
How to apply for the married person's allowance
Separate assessment (default)
No special application is needed. State your marital status in the Tax Return - Individuals (BIR60) and confirm your spouse's identity card details; the IRD will automatically assess you with the married person's allowance.
Joint assessment
- Log in eTAX or use the paper tax return (BIR60)
- Tick “Joint assessment” in Part 4.4
- Fill in your spouse's name and Hong Kong identity card number
- Submit the tax return
Note: Joint assessment must be applied for again every year, and does not carry over automatically to the next year.
FAQ
Can I claim the married person's allowance in the year I get married?
Yes. The IRD goes by marital status during the year of assessment. As long as the marriage is registered at any time within the 2025/26 year (1 April 2025 to 31 March 2026), you can claim the married person's allowance for that year.
Can I claim if I divorced before filing my return?
Yes. The test is whether you were married at any time during the year of assessment, not your status at the time of filing. If you were married at any time during 2025/26, you can still claim for that year even if you divorced before March 2026.
Can I claim if my spouse is not a Hong Kong resident?
Yes. As long as there is a legally valid marriage, the spouse need not be a Hong Kong permanent resident for you to claim. On a first application, or if the information does not match IRD records, you may need to submit a copy of the marriage certificate.
Can both spouses claim the married person's allowance at the same time?
No. Only one spouse in each couple can claim it; it cannot be claimed twice. If both tick the box, the IRD will automatically allocate it to the more favourable spouse and notify the other to amend.
I forgot to claim the married person's allowance. Can I fix it?
Yes. After receiving the notice of assessment you can call the IRD or submit a written request for correction; you can also complete form IR831 to apply for a correction. Requests are accepted as long as they are made within the assessment period.
Summary
The core decision on the married person's allowance comes down to one question: joint or separate assessment? When one spouse's income is clearly lower, joint assessment is usually more cost-effective; when both spouses have high incomes, separate assessment almost always saves tax. We suggest running the numbers with your actual income each year before deciding.
If you need help working out the best way to file, or want us to handle the filing application, find out about SetupHK tax filing services.
Further reading:
Salaries tax calculation and personal allowances: a complete guide
Complete conditions for claiming the dependent parent allowance
Tax filing guide for the self-employed / freelancers
Salaries tax provisional tax calculation
Last updated: May 2026