Table of contents
You can claim an allowance for supporting parents or grandparents aged 55 or above who ordinarily reside in Hong Kong. For 2025/26 it is up to HK$100,000 per dependant; the amounts increase from 2026/27, and each dependant can be claimed by only one taxpayer.
Key takeaways
- You can claim the dependent parent allowance for supporting parents, grandparents or maternal grandparents aged 55 or above who ordinarily reside in Hong Kong.
- 2025/26: HK$50,000 per dependant aged 60 or above; HK$25,000 per dependant aged 55 to 59.
- If the full-year continuous co-residence condition is met, an additional allowance of the same amount can be claimed, up to HK$100,000 in total per dependant.
- From 2026/27 the amounts increase: the age 60 group rises to HK$55,000 and the age 55–59 group to HK$27,500.
- Each dependant can be claimed by only one taxpayer and the allowance cannot be shared.
What is the dependent parent allowance?
The dependent parent allowance and the dependent grandparent or maternal grandparent allowance are among the family member allowances under Hong Kong's salaries tax system. If a taxpayer or their spouse supports an eligible elderly person, the corresponding allowance can be claimed for each dependant, directly reducing assessable income.
The dependent parent allowance and the dependent grandparent or maternal grandparent allowance are tiered by the dependant's age. For 2025/26 it is HK$50,000 per dependant aged 60 or above and HK$25,000 per dependant aged 55 to 59. If the dependant lives with the taxpayer continuously throughout the year and does not have to bear the full cost, an additional allowance of the same amount can be claimed, up to HK$100,000 in total. Each dependant can be claimed by only one taxpayer.
This article focuses on the claim conditions, the definition of living together, sharing arrangements and filing practice for the dependent parent allowance.
For an overview of how salaries tax is calculated overall and the other allowances, see Salaries tax calculation and personal allowances: the complete guide.
Allowance amounts for 2025/26 at a glance
| Dependant's age | 2025/26 allowance | 2026/27 allowance |
|---|---|---|
| Aged 60 or above, or eligible to claim an allowance under the Government's Disability Allowance scheme | HK$50,000 | HK$55,000 |
| Aged 55 or above but under 60 | HK$25,000 | HK$27,500 |
Additional allowance (see the full-year continuous co-residence condition below): same amounts as in the table above, and can be added on top.
| Dependant's age | Additional allowance (2025/26) | Additional allowance (2026/27) |
|---|---|---|
| Aged 60 or above | HK$50,000 | HK$55,000 |
| Aged 55 to 59 | HK$25,000 | HK$27,500 |
💡 SetupHK tip: If the dependent parent is aged 60 or above and lives with you continuously throughout the year, the basic plus additional allowances total HK$100,000 deductible. From 2026/27 this rises to HK$110,000, so you can plan next year's filing in advance.
Source: Inland Revenue Department, Allowances, Deductions and Tax Rates table, 2025/26 and 2026/27.
Three conditions for claiming (all must be met)
To claim the dependent parent allowance, the dependant must meet all three of the following conditions during that year of assessment:
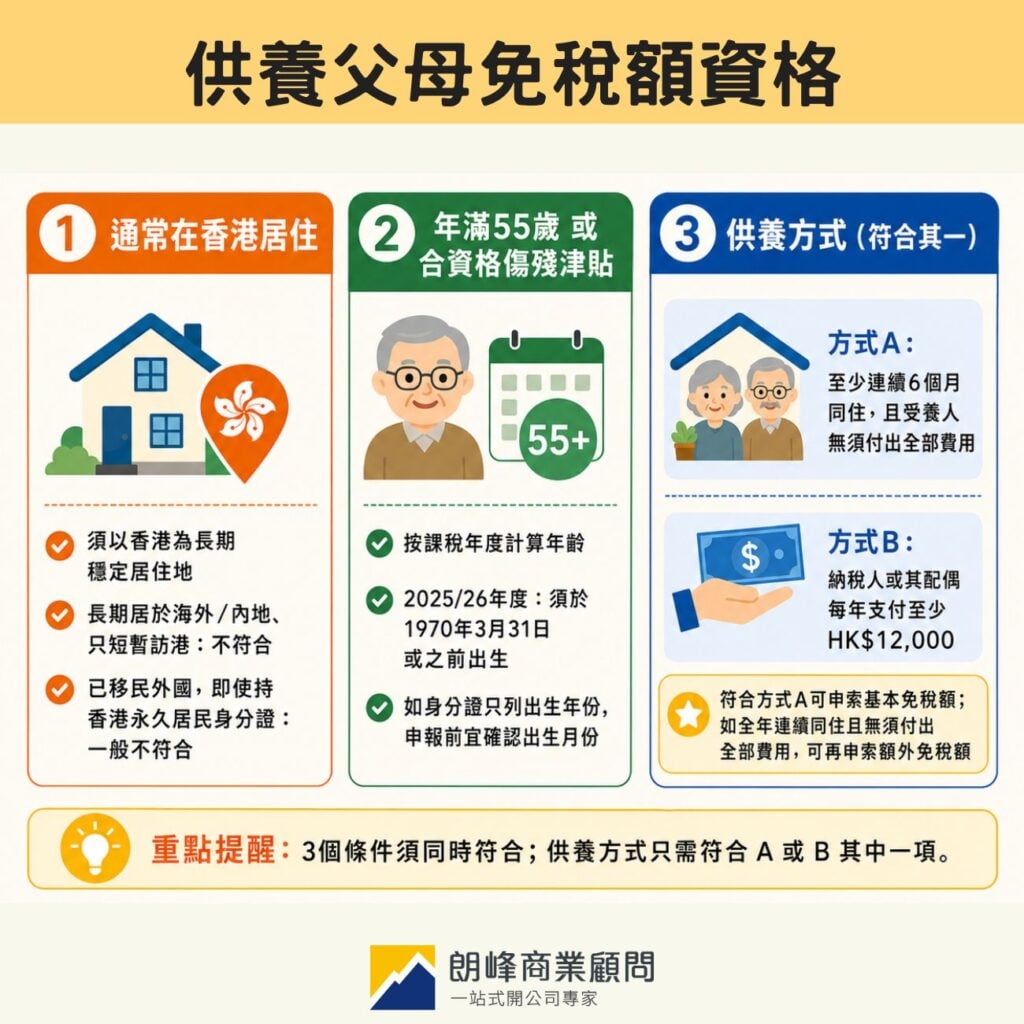
Condition 1: ordinarily resident in Hong Kong
The dependant must treat Hong Kong as their long-term, settled place of residence. The following situations do not meet this condition:
- Living long-term overseas or in Mainland China and visiting Hong Kong only briefly each year
- Having emigrated abroad, even if still holding a Hong Kong permanent identity card
To claim the dependent parent allowance, the dependant must have ordinarily resided in Hong Kong during that year of assessment. Elderly people whose long-term residence is overseas or in the Mainland do not meet this condition, even if they hold a Hong Kong permanent identity card.
Condition 2: aged 55 or above, or eligible to claim an allowance under the Government's Disability Allowance scheme
Age is calculated by year of assessment (1 April to 31 March of the following year). Taking 2025/26 as an example, the dependant must have been born on or before 31 March 1971 to meet the age-55 condition.
If the dependant's identity card shows only the year of birth and not the month, we suggest confirming the month of birth with the dependant before filing.
Condition 3: form of support (meet either one)
Option A: The dependant has lived with the taxpayer for at least 6 consecutive months and does not have to bear the full cost.
Option B: The taxpayer or their spouse pays at least HK$12,000 a year towards the support of the person concerned.
Meeting Option A already entitles you to claim the basic allowance; if, during that year of assessment, the dependant lives continuously throughout the year with the taxpayer and does not have to bear the full cost, you can also claim the additional allowance.
Definition of living together: what counts and what does not?
For the dependent parent allowance, “living together” is limited to long-term co-residence in the same residential unit. Parents living in another unit in the same building, in a nearby estate, or in a separate unit whose rent they pay themselves do not meet the definition.
The definition of “living together” is strict. The following common situations do not qualify: do not meet:
- Parents living in another unit in the same building (including the floors above or below)
- Parents living on a nearby street or in a neighbouring estate
- A separate unit whose rent is paid by the parents themselves
- Staying overnight temporarily for any reason without living together long-term
In short, living together means long-term co-residence in the same residential unit, with the costs borne or shared by the taxpayer.
If my parents are in a residential care home, can I still claim?
Where parents live in a residential care home, home for the elderly or similar institution, since they do not meet the definition of living together, and the fees are charged by the home, you cannot claim the dependent parent allowance.
If your parent is aged 60 or above, or eligible to claim an allowance under the Government's Disability Allowance scheme, you can consider claiming the Deduction for elderly residential care expenses, which is capped at HK$100,000 per dependant for 2025/26 and rises to HK$110,000 from 2026/27.
Note: for the same dependant, the elderly residential care expenses deduction and the dependent parent allowance can only be claimed on an either-or basis, not both at the same time.
Who can claim? Sharing arrangements
The allowance for each dependant can only be claimed by one taxpayer; it cannot be shared among several children or claimed more than once.
It is advisable for the child with the higher assessable income to claim, to maximise the tax saving (under the progressive salaries tax rates, the higher the marginal rate, the greater the benefit of the deduction).
Special case: parents of a deceased spouse
If the spouse has died, the claimant can continue to claim as long as they live with the deceased spouse's parents and support them.
Spouse is not a Hong Kong resident
If the spouse is not a Hong Kong resident but their parents meet the claim conditions (such as living together continuously for six months), the taxpayer can still claim the dependent parent allowance on the spouse's side. As the spouse does not hold a Hong Kong identity card, copies of the spouse's proof of identity and marriage certificate must be provided when filing; if the spouse is later issued a Hong Kong identity card, the IRD must be notified in writing within one month.
How to file, and later spot checks
When submitting the tax return you do not need to attach supporting documents straight away; simply fill in the relevant details in Part 12.4 of the Tax Return - Individuals (BIR60).
The IRD may later carry out a spot check, in which case you will have to provide:
- Copy of the dependant's Hong Kong identity card
- Bank statements (showing a record of regular contributions)
- Proof of living at the same address during the year concerned (such as utility bills or a tenancy agreement)
- Rent receipts for the dependent parents' residence (if applicable)
The IRD will check whether the information is consistent with past records and will confirm travel records through the Immigration Department. Always file truthfully.
What if I filled in the return wrongly or left something out?
The IRD allows taxpayers to correct filing errors or omissions within 6 years after the end of the year of assessment:
| When | How to handle it |
|---|---|
| After submitting the tax return and before receiving the notice of assessment | Submit a written request for amendment to the Assessor |
| After receiving the notice of assessment | Complete IRD form IR831 to apply for a correction |
| After paying the tax | Submit a written correction request to the IRD, and submit form IR6071 to claim the omitted allowance |
FAQ
Can I claim if my parents are still working or have income?
The claim conditions do not require the dependant to be unemployed or to have no other income. As long as the three conditions of residence, age and form of support are met, parents who are still working or have income do not affect your eligibility.
Can siblings agree to share the parent allowance between them?
No. The allowance for each dependant can be claimed in full by only one taxpayer, and cannot be shared by several people or filed separately for the same dependant.
Can I claim for adoptive parents or step-parents?
Yes. Legally adopted parents and step-parents come within the definition of “parent”; as long as the other claim conditions are met, they can be claimed in the same way.
Can I claim for a godfather or godmother?
No. The definition of “parent” covers only natural parents, legally adopted parents, step-parents and parents of a deceased spouse. Customary godfathers and godmothers, or step-parents without a formal marriage registration, do not meet the definition.
My parent's identity card shows only the year of birth, not the month. How do I confirm whether the age condition is met?
We suggest confirming the month of birth with the dependant. A parent who turns 55 during the 2025/26 year of assessment (i.e. 1 April 2025 to 31 March 2026), that is, someone born between January and March 1971, meets the condition; those born between April and December 1971 have not yet turned 55 in 2025/26.
What are the consequences of making a false claim for the dependent parent allowance?
Under section 80(2)(b) of the Inland Revenue Ordinance, anyone who makes an incorrect return without reasonable excuse is liable on conviction to a fine of up to HK$10,000, plus a further penalty equal to three times the amount of tax undercharged; where fraud is involved, imprisonment of three years may also be imposed. For IRD prosecution cases, see the IRD website.
Summary
The key to claiming the dependent parent allowance is the three conditions (ordinary residence in Hong Kong, age and form of support), all of which must be met. The definition of living together is also strict, so confirm the dependant's actual living situation before filing. Where parents live in a residential care home, you can consider the elderly residential care expenses deduction instead.
If you need help clarifying your personal tax position or want us to handle your filing, find out about SetupHK tax filing services, or contact the SetupHK team directly via WhatsApp.
Further reading:
Salaries tax calculation and personal allowances: a complete guide
Married person's allowance and joint assessment: a guide
Tax filing guide for the self-employed / freelancers
Salaries tax provisional tax calculation SetupHK tax filing services
Last updated: May 2026