Table of contents
Rejections of Hong Kong company account applications mostly come down to these four points: a higher-risk business nature, incomplete documents, concerns about a director's background, or proof of address that does not meet the requirements.
Key takeaways
- Reasons for rejection: unclear nature of business, document problems, directors' background, invalid proof of address
- Proof of address must be issued by a government body or financial institution and dated within the last 3 months
- Applications from non-Hong Kong resident directors are harder and require additional proof of business ties to Hong Kong
- Virtual banks have a simple account opening process but limited functions, so choose according to your business needs
- How hard is it to open a Hong Kong company account? The current picture at a glance
How hard is it to open a Hong Kong company account? The current picture at a glance
Many founders have recently assumed that once a company is successfully registered, opening a bank account is a mere formality. In fact, in recent years Hong Kong banks have, under Hong Kong Monetary Authority anti-money laundering (AML) regulatory pressure, significantly tightened their vetting standards. The average processing time for SME account applications has stretched to 4–8 weeks, and complex cases can exceed 3 months; many newly formed companies are turned away at their first attempt.
Industry feedback generally indicates that some traditional banks reject new companies at quite a high rate, and scrutiny is stricter still for companies involved in cryptocurrency, cross-border e-commerce or non-Hong Kong customers.
The banks' core concern is just one: does this company have a genuine business? Is the flow of funds lawful and explainable? All vetting standards revolve around these two points.
Requirements and documents for applying for a company bank account
Basic application requirements
Before applying, first check whether the company meets the banks' basic thresholds. The following 4 points are standard requirements across the major banks, and none can be missing:
- The company has been formally registered with the Hong Kong Companies Registry and holds a valid Certificate of Incorporation (CI) and Business Registration Certificate (BR)
- At least one director is a natural person (not all corporate shareholders)
- Directors and shareholders can attend the bank's account-opening interview in person (some banks can arrange a video interview)
- The company is not in a restricted industry (for example, it is not engaged in regulated businesses such as money lending or remittance without a licence)
Documents required for account opening (overview of 3 categories)
Account-opening documents fall broadly into 3 categories, as shown in the table below for your reference:
| Document type | Main contents | Remarks |
|---|---|---|
| Company statutory documents | Certificate of Incorporation (CI), Business Registration Certificate (BR), Articles of Association (M&A), list of shareholders and directors | Certified true copies (CTC) required |
| Director/shareholder identity documents | Original Hong Kong ID card or passport, proof of address (utility bill or bank letter dated within the last 3 months) | Foreign directors must additionally provide proof of residential address |
| Business description documents | Business plan or business description letter, customer/supplier list (may be anonymised), sample contracts or quotations | These documents are often the key to whether the account opening succeeds |
For a more detailed document checklist, please see the articles below.
Further reading: “What documents are needed to open a company bank account? 3 categories of documents to help you open a corporate account quickly”
Choosing the right type of bank
Account-opening thresholds vary significantly between Hong Kong banks, and choosing the wrong type often hurts more than missing documents, especially as a rejection record from a large bank may affect other banks' impression during their review.
| Bank type | Representative examples | Account-opening threshold | Best suited to |
|---|---|---|---|
| Large traditional banks | HSBC, Bank of China, Hang Seng Bank | Strictest; interview required; review takes 1–4 weeks | Companies with established businesses, regular customers and a transaction record |
| Small and medium-sized local banks | Dah Sing Bank, Bank of East Asia | Relatively relaxed; some can review by mail | Start-ups and businesses with simpler local operations |
| Virtual banks | Airwallex, Aspire, Payoneer | Fully online application; faster review (a few days to 2 weeks) | Cross-border payments, e-commerce and start-ups; higher acceptance |
4 reasons company account applications are rejected
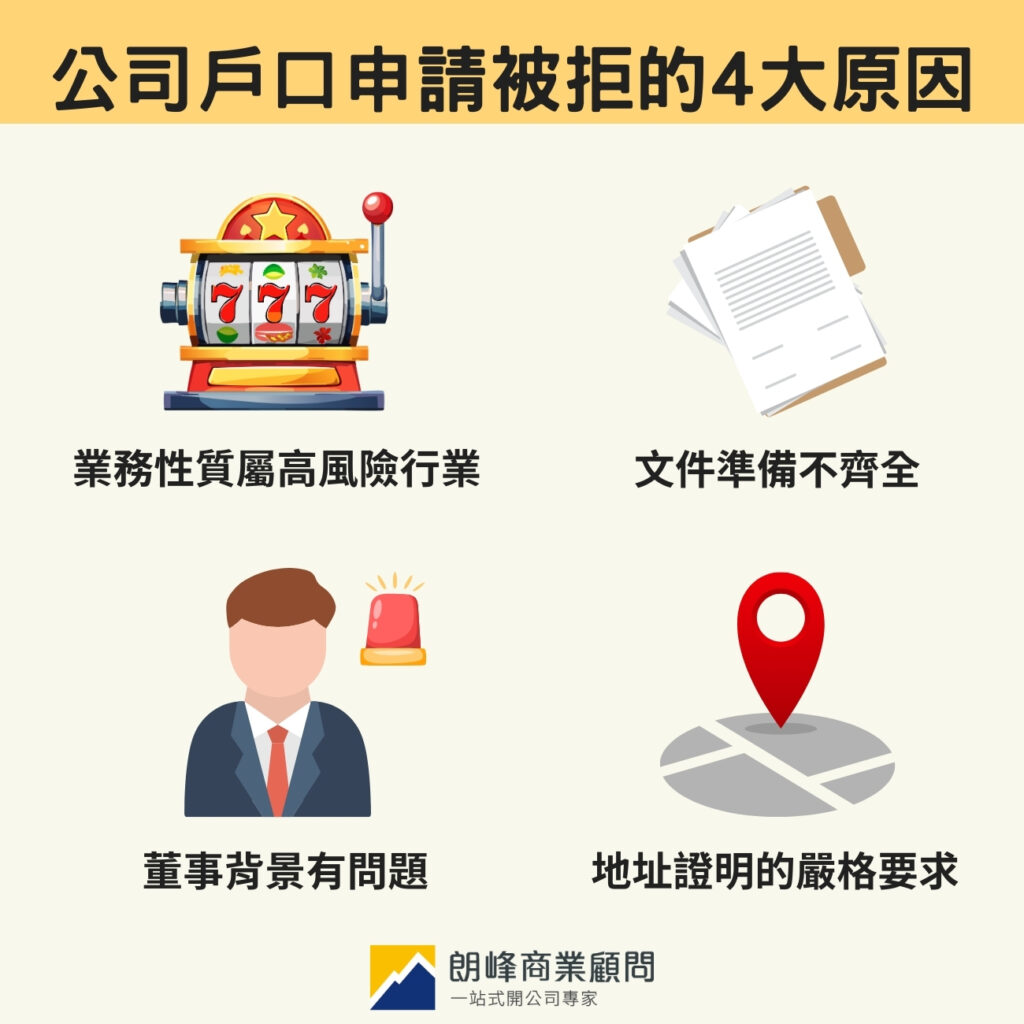
Reason 1: Unclear nature of business or high-risk industry
Banks need to clearly understand “what business the company does, where the money comes from and where it goes”. If the business description is vague, or the business itself falls into a category the bank defines as high-risk, the application is often blocked at the first hurdle.
Business types commonly regarded as high-risk:
- Cryptocurrency-related businesses (trading, wallets, NFT platforms)
- Cross-border remittance or currency exchange
- Main customers from sanctioned countries or regions
- Business involving large cash transactions
- Description too general (for example, only “engaged in trading”, with no specifics on goods and counterparties)
Before applying, prepare a 1–2-page business description setting out what the company does, where its main customers are, the payment methods and the flow of funds. This document often affects the outcome more than all the other documents combined.
Reason 2: Incomplete documents
Even fully compliant businesses are often turned away over document problems. The most common cases:
- Proof of address dated more than 3 months ago, or an unacceptable document type (such as a handwritten receipt)
- Company documents without certified true copies (CTC)
- The director's signature does not match the spelling of the name on the ID card
- Articles of Association (M&A) not updated to the current shareholding structure
Reason 3: Problems with directors' background
Banks run background checks (KYC) on every director and major shareholder. The following situations will greatly reduce the chance of success:
- Directors or shareholders from countries the FATF classes as high-risk
- A director has a problematic personal credit record, or has been blacklisted by a bank
- Complex shareholding structure (for example, multiple layers of holding companies), making it hard to trace the ultimate beneficial owner (UBO)
- A director cannot attend the interview in person, or is vague in the interview and cannot explain the business clearly
If the company's shareholding structure involves an overseas holding company, we recommend preparing the full set of documents and a structure chart for that company in advance, so the bank can clearly trace it through to the ultimate natural-person owner.
Reason 4: Strict requirements for proof of address
Banks are quite strict about proof of address. It must be an official document issued within the last 3 months by a government body, a utility company or a financial institution, clearly showing the applicant's name and residential address.
The following documents are usually not accepted:
- Mobile phone bills
- Letters from insurance companies
- Online shopping platform statements
If a director is a tenant or lives with family and cannot provide a bill in their own name, they can use a monthly bank statement, or an address declaration issued by the landlord or a family member, submitted together with that person's proof of identity and proof of address. Confirming the acceptable document types with the target bank before applying can save you a wasted trip.
Further reading: “[Registered address] Can a virtual office be used as a business registration address? Requirements and how to change the address explained””
SetupHK's friendly reminder: 4 tips to improve your company account opening success rate
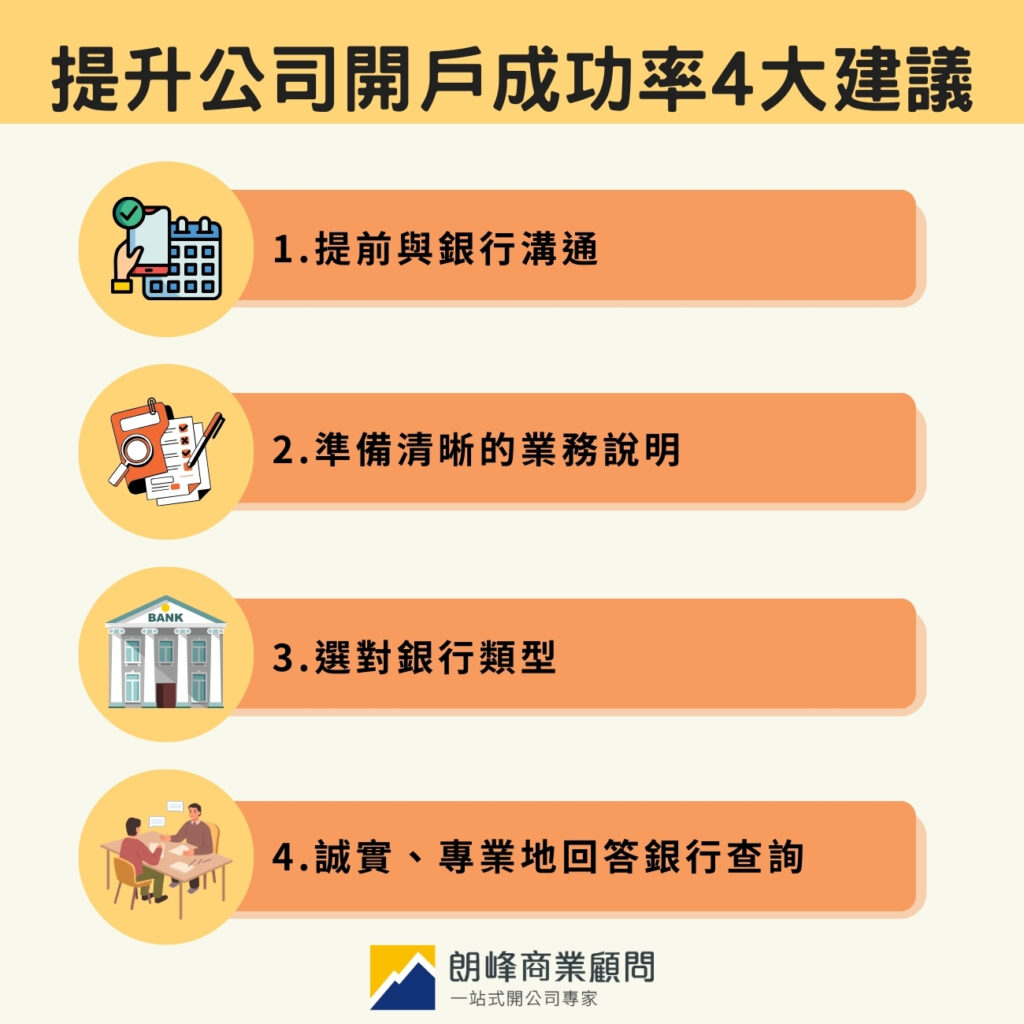
- Talk to the bank in advance
Before applying, contact the relationship manager to find out the bank's account opening policy for your industry. Some banks have internal restrictions on certain industries, and checking in advance avoids wasting time.
- Prepare a clear business explanation
Be able to clearly answer questions about your business model, sources of income, target customers and expected transaction volume, and attach your website, promotional materials or letters of intent. The bank's core question is just one: “Does this company have a genuine business?”
- Answer the bank's enquiries honestly and professionally
Answer the bank's enquiries truthfully, and do not be vague or deliberately evasive. Good communication helps build trust, and trust is often the key to getting approved.
- If rejected, apply again once you understand why
After being rejected by one bank, don't immediately apply to several banks at once. First find out why you were rejected, fix the problem, and then reapply; the success rate will improve significantly.
FAQ
How long does account opening take?
Generally 4-8 weeks, and complex cases may take more than 3 months. Virtual banks usually approve faster, and some cases can be completed within a few working days.
Can I open more than one account at the same time?
Yes. A business can open accounts with different banks according to its needs. For example, you can use a traditional bank for your main business and a virtual bank for day-to-day receipts, combining them flexibly.
Can I apply again after being rejected?
Yes, but we recommend first finding out why you were rejected and applying to another bank after fixing the problem. Applying repeatedly to the same bank within a short period usually has a low success rate.
What is the difference between a virtual bank and a traditional bank?
Virtual banks have a simpler account opening process, but they usually do not support cheque services, cash deposits or international telegraphic transfers, and their daily transaction limits are lower. Traditional banks offer fuller services and suit businesses with complex transaction needs.
Two options for company accounts: digital business accounts and traditional banks
Anti-money laundering (AML) rules have grown stricter in recent years, so opening a company bank account is not always straightforward. SetupHK can help you prepare documents and arrange an account-opening appointment.
Digital business accounts

Airwallex Multi-currency accounts for convenient global payments 
Aspire Business accounts and company cards designed for start-ups 
Payoneer Receive payments from e-commerce platforms and overseas customers 
AsiaPay Let your online shop accept credit card payments
Traditional banks
*The outcome of an account application depends on factors such as the applicant's financial position, the company's industry and minimum deposit requirements. The bank has the final say on whether to open an account.
Account rejected? SetupHK helps you get it right in one go
A rejected application is often not a documents problem but a problem with the direction of preparation. SetupHK provides bank account opening assistance covering pre-application assessment, document preparation, bank selection advice and interview coaching, to address the real cause and improve your chances of success. For more details, feel free to Enquire.
Further reading: “Complete guide to forming a company in Hong Kong: process, costs and key points”